Bank of Canada Interest Rate Decision (September 2026): What It Means for Canadian Homeowners and Businesses
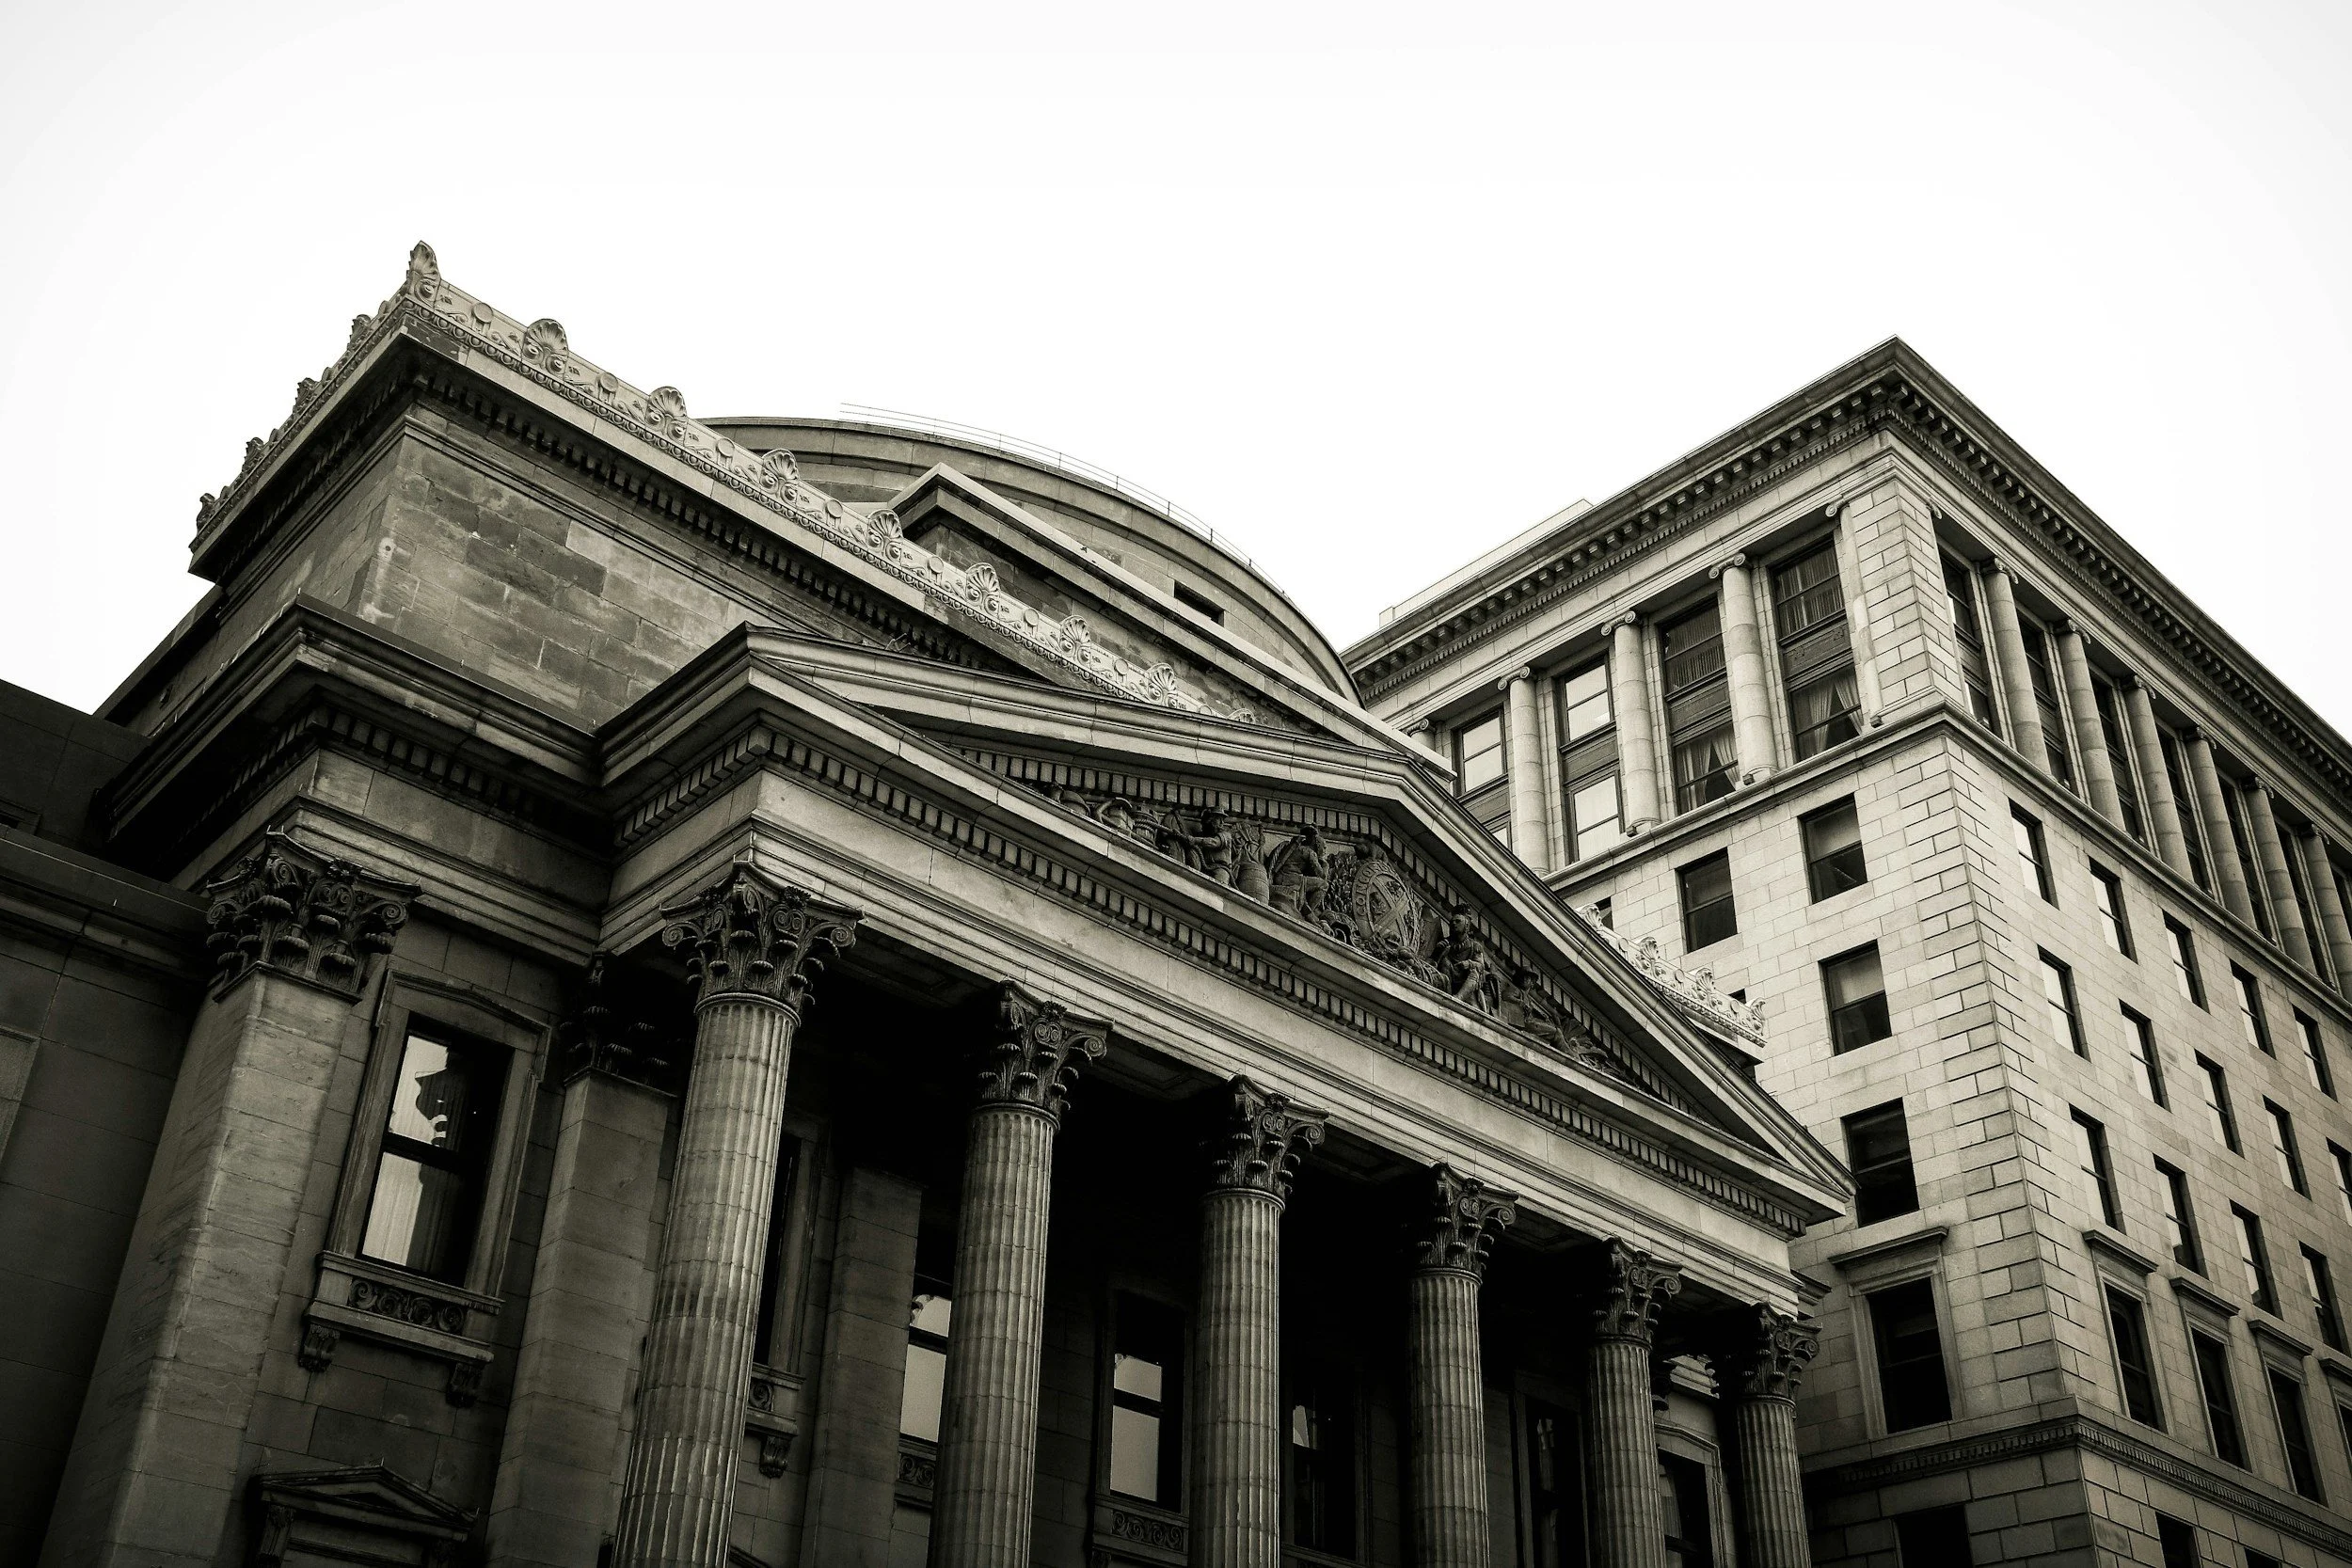
The Bank of Canada headquarters in downtown Ottawa, where Governing Council meets to set national interest rates.
What is the Bank of Canada's key interest rate right now?
On September 2, 2026, the Bank of Canada (BoC) held its key policy interest rate steady at 2.25%. The Bank Rate remains at 2.50%, and the deposit rate sits at 2.20%. This marks the seventh consecutive interest rate hold by the central bank.
Key Takeaways: September 2026 BoC Rate Hold
Policy Rate: Maintained at 2.25%.
Prime Rate Impact: The prime rate at major Canadian financial institutions (RBC, TD, Scotiabank, BMO, CIBC) remains unchanged.
Economic Growth: Canadian GDP rebounded strongly in Q2 2026 at an annualized 3.3%.
Core Drivers: While underlying inflation sits close to the 2.0% target, persistent global energy disruptions and new cross-border tariffs create upward inflation risks.
Why Did the Bank of Canada Keep Rates at 2.25%?
In its official rate announcement on September 2, 2026, Governing Council noted that the Canadian economy is evolving largely in line with projections. Following a quiet start to the year, economic output rebounded sharply in the second quarter, buoyed by stronger consumer spending, improved hiring, and increased business investment.
However, two major macroeconomic risks prevented further monetary easing:
Global Supply & Energy Volatility: Geopolitical conflicts in key energy regions continue to keep fuel prices volatile.
Trade Disruptions & Tariffs: Emerging tariff developments between Canada and the U.S. have introduced cost pressures for Canadian importers and exporters.
By holding rates steady, the Bank aims to balance economic expansion with headline inflation control.
How This Decision Impacts You Across Canada
1. Variable-Rate Mortgage Holders
If you hold a variable-rate mortgage or a Home Equity Line of Credit (HELOC) with a Canadian lender, your borrowing costs remain unchanged this month. Because prime rates stay tied to the overnight rate, your monthly payments (or the portion applied to your principal),will remain stable.
2. Fixed-Rate Mortgage Seekers & Home Buyers
Fixed mortgage rates are influenced primarily by Government of Canada bond yields rather than the central bank's overnight target. With 5-year bond yields holding steady around the mid-3% range, 3-year and 5-year fixed mortgage rates across major regional hubs, from the Greater Toronto Area (GTA) and Metro Vancouver to Calgary, Montreal, and Atlantic Canada, are staying within current competitive brackets.
3. Canadian Small Businesses
Stable interest rates provide a predictable lending floor for business lines of credit and commercial equipment loans. Canadian entrepreneurs planning Q4 capital expenditures can budget without immediate fear of rate hikes.
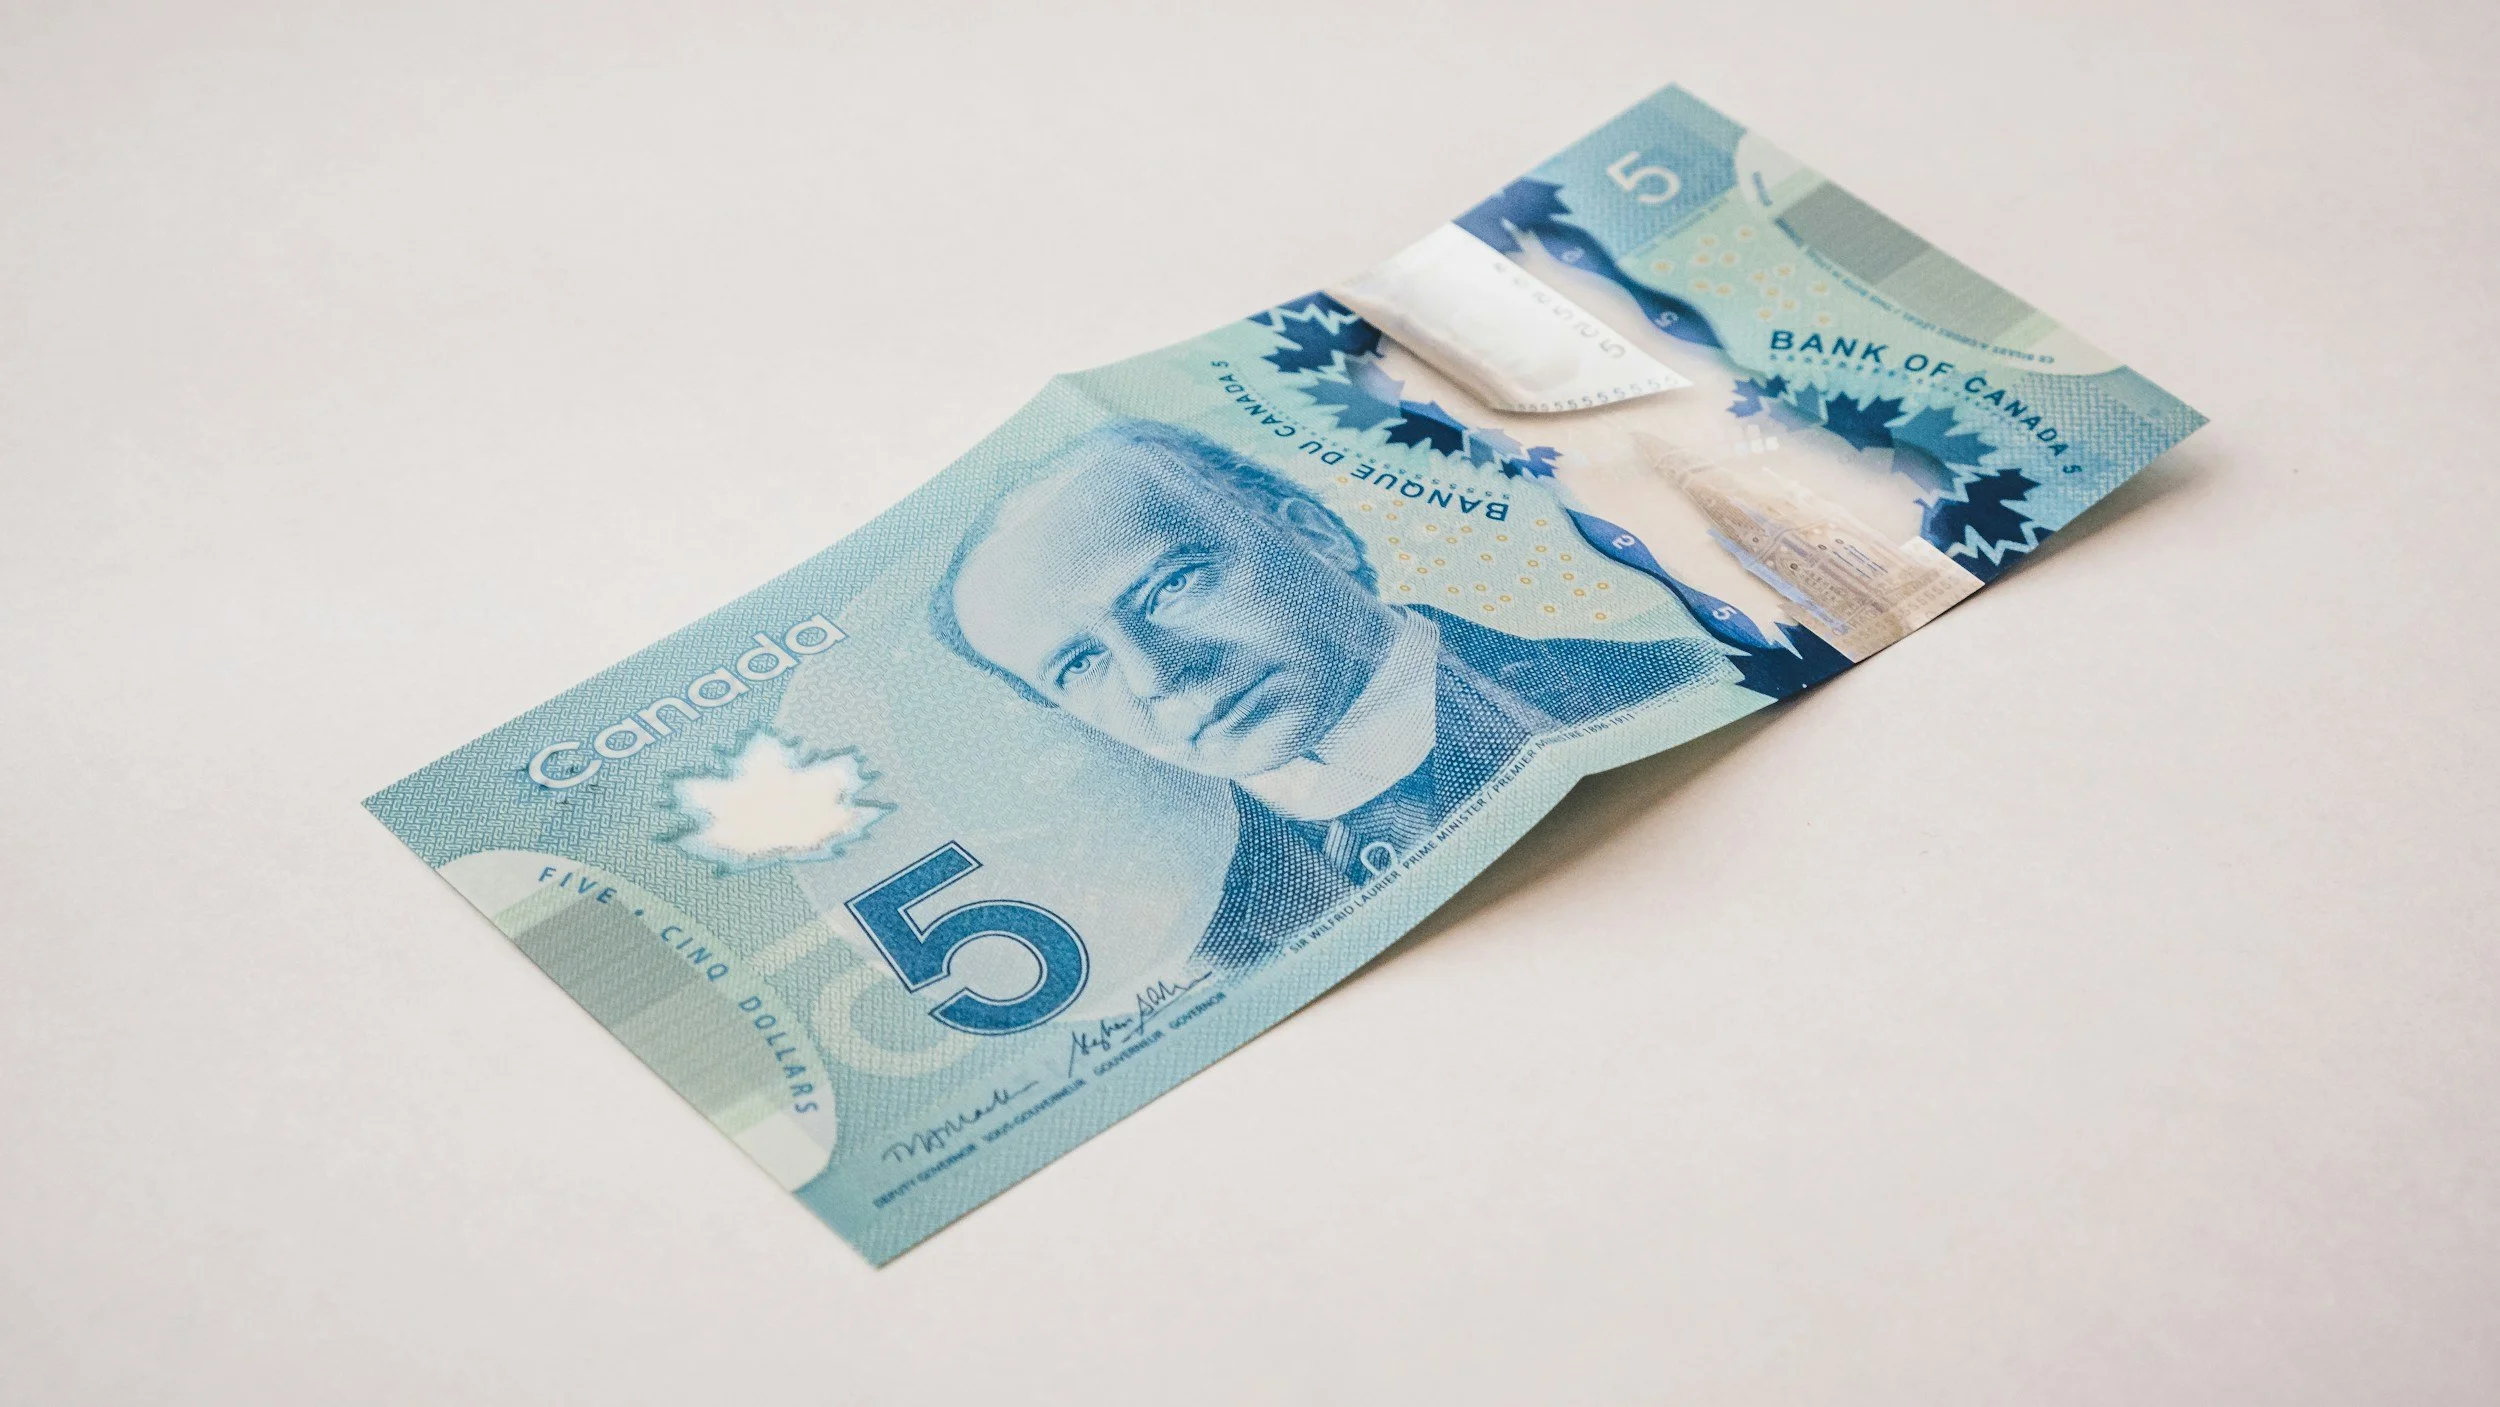
The blue polymer Canadian $5 note, featuring Sir Wilfrid Laurier on the front and Canadarm2 on the back
Frequently Asked Questions (Q&A)
Q1: When is the next Bank of Canada interest rate announcement?
A: The next scheduled Bank of Canada interest rate decision is Wednesday, October 28, 2026. This announcement will also be accompanied by the full Monetary Policy Report (MPR).
Q2: Will interest rates go up or down in Canada by the end of 2026?
A: Most financial analysts expect the Bank of Canada to remain on hold through late 2026. While headline inflation sits near target, potential tariff risks and energy prices mean Governing Council is taking a wait-and-see approach.
Q3: Should I choose a fixed or variable mortgage rate right now?
A: Choosing between a fixed and variable rate depends on your risk tolerance and financial horizon. A fixed rate offers payment certainty, whereas variable rates offer flexibility if central bank monetary policy shifts toward rate cuts in 2027. Speak with a licensed mortgage broker to evaluate your specific scenario.
Take Action on Your Financial Strategy Today
Whether you are renewing a mortgage, planning a home purchase, or restructuring business debt in today's interest rate environment, having expert guidance ensures you never overpay.
Have questions about how the latest Bank of Canada rate decision affects your mortgage or business cash flow? Contact our expert advisory team today for a customized financial review.
